
Introduction
Uninsured drivers can complicate Seattle car accident claims by making compensation harder to recover, creating additional insurance procedures, and increasing disputes over fault and damages. Even when another driver causes a collision, injured victims may struggle to cover medical bills, lost wages, and vehicle repair costs because no liability insurer is available to pay for their losses.
Seattle has busy traffic corridors, including Interstate 5, Interstate 90, and State Route 99, where commuters and commercial vehicles share the road. Downtown intersections often involve pedestrians, cyclists, and turning vehicles, making collisions more complicated to investigate. The city’s frequent rain can also reduce visibility and make roads slippery.
When an uninsured driver causes a crash in these conditions, a Seattle car accident lawyer can help injured people understand their legal options and explore possible sources of compensation.
Compensation Can Be Difficult to Recover
When an insured driver causes a collision, the injured person can generally pursue a claim through the at-fault driver’s liability insurance. Without that coverage, there may be no insurance company available to pay a settlement for medical expenses, vehicle damage, lost income, or other eligible losses.
The uninsured driver may also lack the personal assets needed to cover significant damages. Although an injured person may consider filing a lawsuit, obtaining a judgment does not guarantee that the money can be collected. This uncertainty can make financial recovery more challenging, especially when injuries require ongoing treatment or prevent someone from returning to work.
Your Own Insurance May Become More Important
When the other driver has no insurance, your own policy may become a primary source of potential compensation. Uninsured motorist coverage may help pay for certain accident-related losses, depending on the policy, coverage limits, and circumstances. Collision coverage may also help pay for vehicle repairs, although a deductible may apply.
Washington law, including Revised Code of Washington (RCW) 48.22.030, addresses uninsured and underinsured motorist coverage. However, coverage is not automatic for every expense or situation. Your insurer may need to investigate the collision, confirm the other driver’s insurance status, and evaluate the injuries and damages before deciding what benefits apply.
These additional requirements can create paperwork, delays, and disagreements that would not arise in the same way when the at-fault driver’s insurer handles the claim.
Establishing Fault Still Matters
An uninsured driver is not automatically responsible for a collision simply because they lack coverage. The injured person must still establish how the accident occurred and demonstrate the losses connected to it.
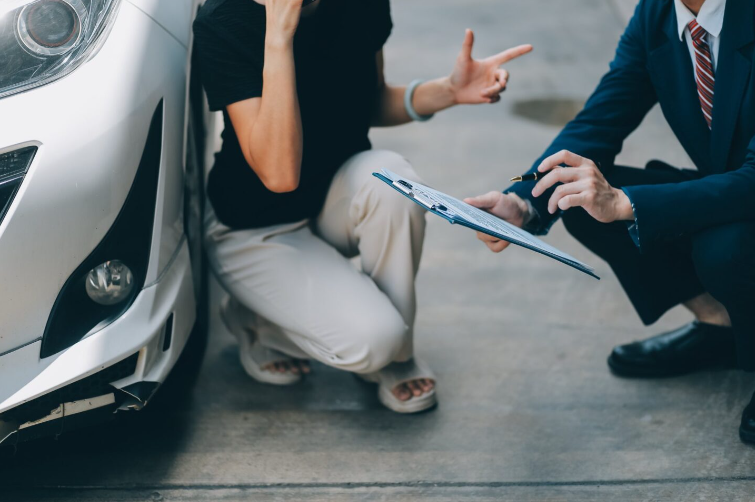
Photographs of vehicle damage, witness statements, police reports, medical records, and dashcam footage can help clarify what happened. Keeping receipts for treatment, vehicle repairs, transportation, and other expenses can also support a claim.
Washington follows comparative fault principles. Under RCW 4.22.005, a person’s own share of fault can reduce their recoverable damages proportionately. If the drivers disagree about who caused the crash, evidence may become especially important in determining responsibility and evaluating compensation.
How Legal Guidance Can Help
Insurance disputes can become more difficult when the other driver is uninsured, the injuries are serious, or multiple parties may share responsibility. A car accident lawyer may review available evidence, explain applicable coverage, communicate with insurers, and help assess whether a settlement fairly reflects the documented losses.
Legal guidance can also help identify important deadlines and explain whether pursuing a claim against the uninsured driver is practical. The right approach depends on the available insurance, the severity of the injuries, and the evidence supporting liability.
Steps to Take After a Collision
After a crash, seek medical attention when necessary and report the accident as appropriate. Photograph the scene if it is safe, collect witness information, preserve relevant video footage, and keep copies of medical and repair records. Notify your insurer promptly and ask which coverage options may apply.
Avoid assuming that no compensation is possible just because the other driver lacks insurance. Reviewing your policy and understanding the available legal options can help you decide what to do next.
Key Takeaways
- Uninsured drivers can make compensation harder to recover because liability insurance may not be available.
- Your own uninsured motorist or collision coverage may offer alternative options.
- Evidence is still necessary to establish fault and document losses.
- Insurance investigations and coverage disputes can delay claims.
- Preserve records and review your policy promptly to understand your options.